Listen to this podcast in the app for free: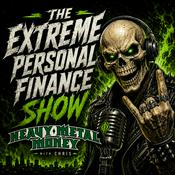 Download for free in the App Store
radio.net
Sleep timer
Save favourites
135 episodes
Don’t Wait to Retire: How to Get Your Time Back With Brian Herriot | 120
23/10/2026 | 43 mins.Don’t Wait to Retire: How to Get Your Time Back With Brian Herriot
What if you didn’t have to wait until 65 to get your life back? In this episode of The Extreme Personal Finance Show, Chris talks with Brian Herriot, financial advisor, former management consultant, and author of Time Freedom: Rethink Your Work and Money to Create a Life You Love Now.
In 2020, Brian ran his numbers after the COVID market crash and found he was still 20 years from financial independence. He and his wife asked a better question: what if we go after control of our time first? By 2023, he was taking his first summer off at a lake cabin in Wisconsin.
In this episode, you’ll learn:
Why financial freedom is “absolute freedom” and time freedom is “meaningful freedom”
The time freedom formula: lifestyle expenses = investment income + flexible work
Brian’s 3-year path from corporate career to a flexible lifestyle business
How to build money confidence and push past scarcity thinking
When using retirement money for a business can make sense, and why Brian says it must be as sure a bet as possible
How to design your lifestyle with the “look back, look ahead” exercise and four key life areas
How to keep time freedom flexible when your family and seasons change
What to do with time freedom once you have it (the “call to greatness”)
Practical moves for W-2 employees, from using all your vacation to reading your HR manual
Timestamps
00:00 Intro
02:13 What time freedom means
03:38 Meaningful freedom vs. absolute freedom
05:54 The time freedom formula
09:13 The 3-year path
14:37 Money confidence and scarcity thinking
16:25 When to quit and kill criteria
19:20 Using retirement accounts to invest in yourself
24:28 Designing a lifestyle (budgets never work)
30:34 Keeping time freedom flexible as seasons change
32:32 Is time freedom a privilege story?
37:01 Time freedom for W-2 employees
41:28 The first step to take
42:15 Where to find Brian
Contact Chris:
https://heavymetal.money
https://www.facebook.com/MoneyHeavyMetal
https://x.com/MoneyHeavyMetal
https://www.instagram.com/chrisluger
https://www.tiktok.com/@heavymetalmoney
email: chris at heavymetal.money
Resources and Links:
https://timefreedom.life
Time Freedom Calculator
https://timefreedom.life/help/
Brian’s Substack
https://brianherriot.substack.com
Vision Setting: The Power of a 10-Year Life Plan (Debbie Millman’s “Remarkable Life” Exercise)
https://diewithzerobook.com
Contact Chris:
https://heavymetal.money
https://www.instagram.com/heavy_metal_money/
https://www.youtube.com/@heavymetalmoney
https://www.facebook.com/chrisluger
email: chris at heavymetal.moneyTax Brackets Explained: Why a Raise Never Cuts Your Take-Home Pay [RE-ISSUE] | 119
09/10/2026 | 22 mins.Tax Brackets Explained: Why a Raise Never Cuts Your Take-Home Pay [RE-ISSUE] | 119
Episode Summary:
This is a re-issue from a few years ago and it has been one of my favorite episodes. My late friend Dan did such a great job in explaining how our progressive tax brackets work. Ever turned down overtime, a side gig, or a promotion because you were afraid of landing in a higher tax bracket? You’re not alone, and you’re also working off a myth.
In this episode of The Extreme Personal Finance Show, Chris is joined by his buddy Dan Hine to break down how the U.S. progressive tax system really works. They use the “bucket” method, picture a faucet filling one bucket at a time, to show why only the dollars inside each bracket get taxed at that bracket’s rate. No, a raise will not leave you with less money in your pocket. There is no 100% tax bracket, folks.
In this episode, you’ll learn:
How progressive tax brackets work, without needing a CPA
The difference between your marginal tax rate and your effective tax rate
Why the “promotion tax penalty” is a myth
Why brackets apply to taxable income, not your salary
How to avoid surprises at tax time with a simple estimation approach
Where to find free tax help if the whole thing still feels overwhelming
2026 Federal Tax Brackets (Single Filers, Taxable Income):
10%: $0 to $12,400
12%: $12,401 to $50,400
22%: $50,401 to $105,700
24%: $105,701 to $201,775
32%: $201,776 to $256,225
35%: $256,226 to $640,600
37%: $640,601 and above
Quick note: These brackets apply to taxable income, which is what’s left after deductions. The 2026 standard deduction for a single filer is $16,100, so someone earning $50,000 gross will not have $50,000 of taxable income.
Resources Mentioned:
Fidelity’s tax bracket article (the faucet and buckets graphic)
IRS: Federal income tax rates and brackets
IRS: 2026 tax inflation adjustments
Free tax help through local libraries and IRS-supported programs
Heavy Metal Money blog: heavymetal.money
Disclaimer: This episode is for educational purposes only and is not tax advice. Talk with a qualified tax professional about your situation.
Contact Chris:
https://heavymetal.money
https://www.instagram.com/heavy_metal_money/
https://www.youtube.com/@heavymetalmoney
https://www.facebook.com/chrisluger
email: chris at heavymetal.moneyBuilding A Life Worth Retiring To with Amberly Grant | 118
02/10/2026 | 43 mins.Building A Life Worth Retiring To with Amberly Grant | 118
What happens when you build a money community and then take it around the world?
What we cover:
Why Amberly started FinTalks in the worst month in modern history to start anything
Turning a weekly Zoom call into cruises, castles, and Antarctica
How travel advisors actually get paid, and why booking through one costs you nothing extra
Group rates, onboard credit, and automatic repricing most people never ask about
The Scotland castle co-working and no-working trip, and the Italy version coming in 2027
Real numbers on the short-term to long-term rental pivot
What killed short-term rentals in Denver, and whether it's coming for your market
Midterm rentals explained, including the insurance placement angle
Renting out your primary residence so you can travel
Financing, house hacking, and the first call every new investor should make
Tenant screening that actually works, including Chris's car trick
Travel as a muscle, and how to build it if you're a homebody
World schooling, green cards, and raising kids who've seen more than one country
This week I'm joined by Amberly Grant, real estate investor, financial educator, and the creator of FinTalks, a weekly money and life community she started in March of 2020. And not just because it seemed like a good idea. Amberly started it while her life was falling apart. She had just left her fiancé, handed over $80,000 to buy him out of their house days before the market dropped, and decided the best thing to do while hurting was to go help other people. Six and a half years later, FinTalks is still meeting every Tuesday.
That community has grown into something wild. It started with in-person meetups in Colorado, turned into a 65-person cruise, then a 120-person cruise, then a two-week co-working and no-working adventure in a Scottish castle with scotch tastings, sheep herding, and race car driving. Now she's got two Caribbean cruises on the books for January 2027, an Italian farmhouse in August 2027, and an Antarctica expedition in 2028 where 57 people have already signed up at $16,500 a head. Amberly thought frugal people would never go for it. She was wrong.
But this episode is not just travel talk. Amberly opens the books on why she's moving her rental portfolio from short-term to long-term, and she does not sugarcoat the cost. At her peak she was clearing about $6,500 a month. By 2025 that was down closer to $4,000. Going long-term costs her another $1,000 to $1,500 a month. She did it anyway, and she explains exactly why: a saturated Denver market, Airbnb support that let her down, guests who started treating her place like a hotel room, three bad stays in a row, a second baby, a full-time job, and a travel business she was building on the side. Something had to go.
We also get into the stuff you can actually use. What a midterm rental is and why insurance placements are one of the best-kept secrets in the game. How Amberly rented her primary residence for $6,000 a month while living in Mexico City with a three-month-old. Why she makes every prospective tenant get on a 15-minute phone call before she'll even schedule a showing, and how that process has kept her properties at basically zero vacancy for six years. Why vetting is the single most important stage of your entire real estate journey. And why you should never, ever do favors for people who give you a sob story, with one exception she'll explain.
Plus the part that hit home for me personally: Amberly's take that travel is a muscle. If you haven't flexed it, of course it feels scary. Start small, start known, and work your way up. As a guy who likes his own bed and gets a knot in his stomach at the airport, I needed to hear that.
Contact Chris:
https://heavymetal.money
https://www.facebook.com/MoneyHeavyMetal
https://x.com/MoneyHeavyMetal
https://www.instagram.com/chrisluger
https://www.tiktok.com/@heavymetalmoney
email: chris at heavymetal.money
Resources and Links:
https://www.amberlygrant.com
https://www.amberlygrant.com/travel-events
https://www.amberlygrant.com/fintalks
Amberly on instagram
https://www.instagram.com/amberlygrant/
Mile High FI Podcast
https://milehighfi.com
CampFI
https://campfi.org
https://www.silversea.com
Contact Chris:
https://heavymetal.money
https://www.instagram.com/heavy_metal_money/
https://www.youtube.com/@heavymetalmoney
https://www.facebook.com/chrisluger
email: chris at heavymetal.moneyHow to Retire on Purpose with Scott Folland | 117
25/09/2026 | 43 mins.How to Retire on Purpose: The Last 6 Months Before Walking Away
What happens when your financial advisor looks you in the eye and says "you could retire today," and you decide to keep working anyway?
My friend Scott Folland is back on the show, and this time he's got a date circled. He's an orthopedic PA here in the Twin Cities, he's been at the same practice for 15 years, and he's clocking out for good in early January. Not because he hates the job. He actually likes it. That's what makes this conversation so different from most early retirement stories you hear.
Scott walks us through the slow downshift, going to 80% time with Fridays off a couple of years back, then spending six months training the person who's taking over his role. We get into the part almost nobody talks about: what happens to your identity when the title goes away. Scott's had three sabbaticals in his career, including two years living overseas in East Africa, so he's had some practice being a person who isn't his job.
Then there's the whiteboard. Scott went through a retirement planning module, decided the "vision board" exercise was corporate nonsense, bought a whiteboard at Target out of spite, and ended up with something that now sits next to his bed where he looks at it twice a day. Three columns: things to add, things to try, and things to cut out of his life entirely. That middle column is the one most people skip.
We also get into the nuts and bolts. Where the money comes from first, why he's letting the 401(k) keep growing even though the rule of 55 is right there, how he's covering health insurance before Medicare, why he shut off his retirement contributions in the final year, and what he's doing with 2,700 miles of gravel road between Mexico and Banff.
Oh, and he's planning to get a job. Two of them. You'll want to hear why.
If you're a few years out and terrified to pull the trigger, Scott's closing advice is worth the whole episode.
Contact Chris:
https://heavymetal.money
https://www.facebook.com/MoneyHeavyMetal
https://x.com/MoneyHeavyMetal
https://www.instagram.com/chrisluger
https://www.tiktok.com/@heavymetalmoney
email: chris at heavymetal.money
Resources and Links:
Stacking Benjamins Podcast
Marks Money Mind Podcast
Earn & Inest Podcast
Faribault Wool Mill Tour
Hostel Movie
Rock Retirement Club
https://www.rockretirementclub.com
Jean Chatsky’s The Forever Paycheck
Life Transitions - Live from CampFI RM Week 3 | Episode 051
https://youtu.be/7i_tGglOv28?si=3HQ2tKU2e2p4Qhz0
Williams Sonoma Coffee Class
Contact Chris:
https://heavymetal.money
https://www.instagram.com/heavy_metal_money/
https://www.youtube.com/@heavymetalmoney
https://www.facebook.com/chrisluger
email: chris at heavymetal.moneyStop Competing, Start Collaborating with Joe Saul-Sehy and Jordan Grumet | 116
18/09/2026 | 31 mins.Stop Competing, Start Collaborating with Joe Saul-Sehy and Jordan Grumet | 116
Joe Saul-Sehy from Stacking Benjamins and Dr. Jordan Grumet (Doc G) from Earn & Invest trashed my place…err I mean crashed at my place during Camp FI Midwest. Naturally, I put freakin’ microphones in front of them!
This one started as a conversation about our joint Benjamins After Dark meetup in the Twin Cities and turned into a full-on masterclass on why collaboration is a money skill. Not a soft skill. A money skill.
Competitor or collaborator? Pick one. Joe tells the story of meeting a brand new finance podcaster at Podcast Movement who wouldn't even say what his show was about. Joe never heard from him again. Being guarded gets you nowhere.
You grow no matter where you sit. Doc G breaks down the mentor, mentee, and peer roles. If someone knows more, they're your mentor. If they know less, you're theirs. Either way, both sides walk away with more than they started with. As they say in medicine: see one, do one, teach one!
Set the goalposts before you start. Collaborations can go sideways because nobody defined what success looked like up front. Different intentions, different audiences, two years of silence. Doc G's take: if one person wants to educate for free and the other wants to charge per download, you need to know that on day one.
Be useful. Joe pulls from Alex Hormozi and Zig Ziglar: become the person people call. In his financial planning days, clients called him for mortgage guys, estate attorneys, even mechanics. That's the whole game.
Open your network or go home. Doc G says a collaborator who won't share their contacts isn't worth their salt. I've seen the opposite in my tech career, people hoarding contacts like dragons on gold. It never works.
Your advisor should be a collaborator. If someone leads with a product instead of asking about your life, that's a sales pitch, not advice. Roger Whitney's line: anyone who leads with product and not process is not an advisor.
Networking is dead. Doc G declares it, and Joe agrees it should be. Replace it with three steps:
Show up somewhere with like-minded people
Listen more than you talk
Be generous with what you know when the time is right.
Friendships over FI numbers. Joe says becoming financially independent was fine. Realizing he had enough people in his corner that they'd never let him fail? That hit way harder.
Collaboration leads to impact. Doc G's closer. We all say we want money and career success. Roll it up and what we really want is impact. Collaboration is how you get there.
Bonus content: a Camp FI travel hacker who turned out to have a PhD in agriculture, Joe getting pizza oven lessons at his sister's birthday party, my uncle refusing to meet my banker at the horse track, and a man in Mankato who volunteers so much people call him Mr. Mankato.
Contact Chris:
https://heavymetal.money
https://www.facebook.com/MoneyHeavyMetal
https://x.com/MoneyHeavyMetal
https://www.instagram.com/chrisluger
https://www.tiktok.com/@heavymetalmoney
email: chris at heavymetal.money
Resources and Links:
Dr. Jordan Grumet
https://jordangrumet.com
Earn & Invest Podcast
https://jordangrumet.com/episodes
Jordan’s Substack
https://substack.com/@jordangrumet
Joe Saul-Sehy
https://joesaulsehy.com
Stacking Benjamins Podcast
https://www.stackingbenjamins.com
Benjamins After Dark Meetup Groups
https://www.stackingbenjamins.com/groups/
CampFI
https://campfi.org
Contact Chris:
https://heavymetal.money
https://www.instagram.com/heavy_metal_money/
https://www.youtube.com/@heavymetalmoney
https://www.facebook.com/chrisluger
email: chris at heavymetal.money
More Business podcasts
Trending Business podcasts
About Extreme Personal Finance Show
Personal finance doesn't have to be boring. We refuse to let it be.The Extreme Personal Finance Show is where financial independence meets a crushing guitar riff. I'm Chris, early retiree, tech guy, and lifelong metalhead. I built this show for people who wanna take control of their money and their lives!We cover everything from building wealth, killing debt, investing for the long haul, side income, real estate, retirement planning, and the mindset shifts that make all of it actually stick. No filler, no BS, no 47-minute intros.Each week I sit down with brilliant guests from the FIRE movement and beyond. These people who've cracked the code and are generous enough to share it. Plus solo episodes where I break down the stuff nobody talks about at the dinner table but everybody needs to hear.This isn't your parents' money podcast. Strap in and hold on tight! HORNS UP! 🤘🤘
Podcast websiteListen to Extreme Personal Finance Show, The Property Academy Podcast and many other podcasts from around the world with the radio.net app
Get the free radio.net app
- Stations and podcasts to bookmark
- Stream via Wi-Fi or Bluetooth
- Supports Carplay & Android Auto
- Many other app features
Get the free radio.net app
- Stations and podcasts to bookmark
- Stream via Wi-Fi or Bluetooth
- Supports Carplay & Android Auto
- Many other app features

Extreme Personal Finance Show
Scan code,
download the app,
start listening.
download the app,
start listening.
Extreme Personal Finance Show: Podcasts in Family
 New Zealand